The Surprise Bill the No Surprises Act Left On the Table
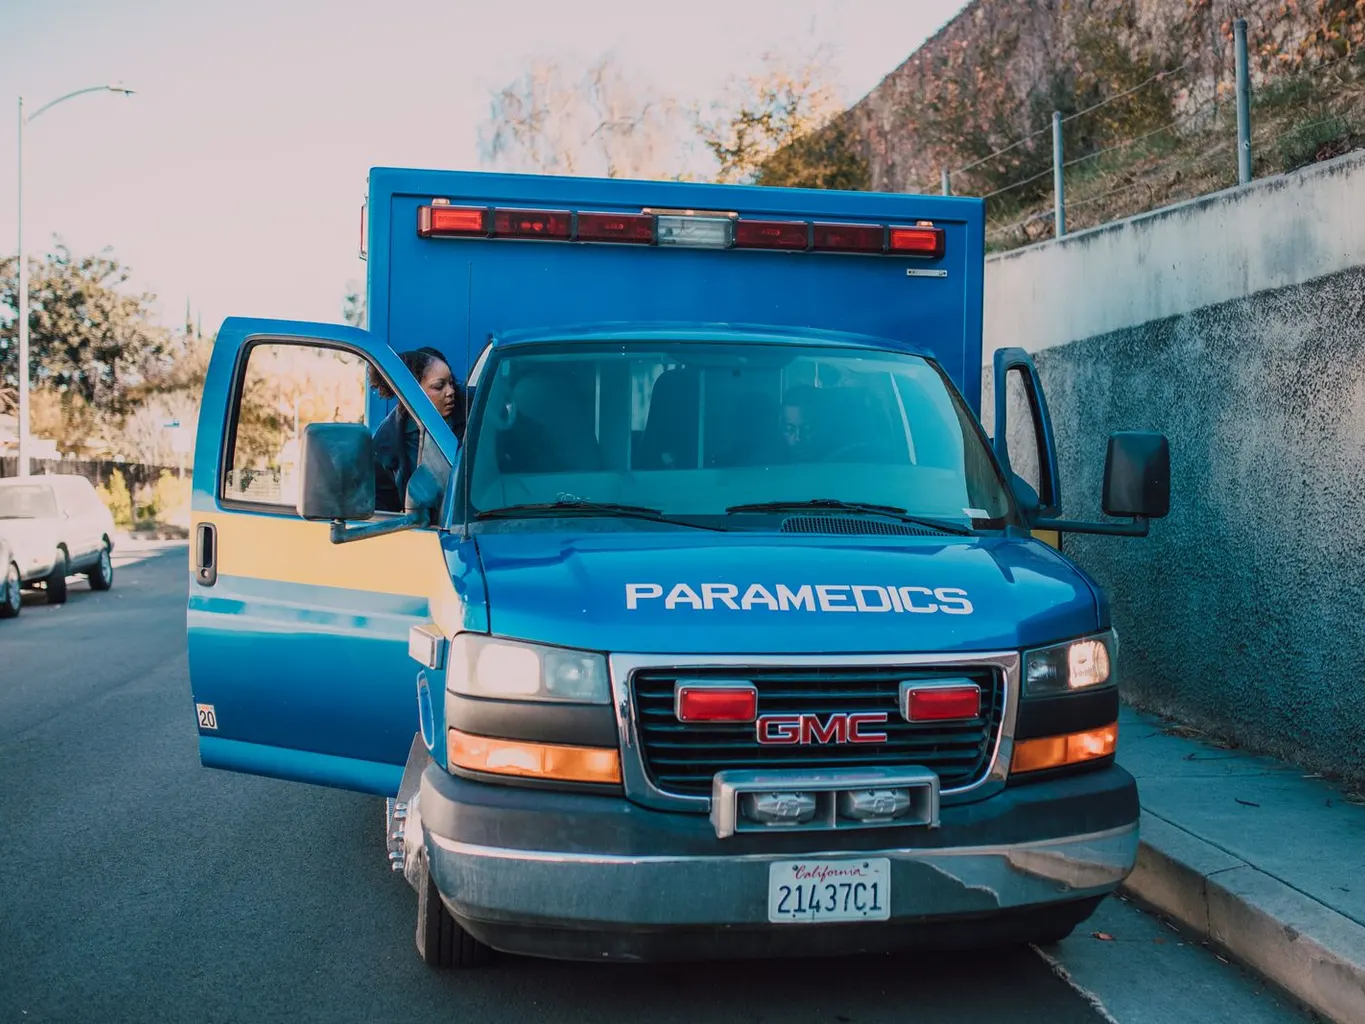
The 2022 law killed most surprise medical bills. It left out the one almost nobody chooses and everyone assumes is covered: the ground ambulance. More than half of those rides come back out of network, and the average balance runs about $450.
You Thought Surprise Bills Were Over
In 2022 a federal law called the No Surprises Act took effect, and it did something genuinely good. If you go to the emergency room, or you get treated at an in-network hospital by an out-of-network doctor you never chose, you can no longer be hit with a surprise balance bill for the difference. That used to happen constantly. Now it mostly does not. Real protection, and it worked.
Here is the part that did not make the headlines. When Congress wrote the law, it left out the ground ambulance. Not the air ambulance, that one got covered. The ordinary ambulance that shows up when you call 911. It was carved out, set aside for a committee to study later, and that gap is still open.
So the one medical service you have the least ability to shop for, that you summon in the worst moment of your day, that you cannot exactly decline when you are on the ground, is the one the law forgot to protect. And more than half the time, the ride comes back out of network.
The Ride You Never Agreed to a Price For
Think about how every other purchase works and then think about an ambulance. You call for one because something is very wrong. You do not get to ask which company is dispatched. You do not get to check whether they are in your insurance network. You cannot compare two of them on price. You are, in many cases, not fully conscious for the transaction.
There is no other corner of American life where you are billed hundreds or thousands of dollars for a service you did not select, at a price you never saw, provided by a company you could not have chosen. And because a huge share of ground ambulance services are run by local governments and fire departments rather than by companies that sign insurance contracts, a majority of them simply are not in anyone's network. The studies that have looked at this keep landing above fifty percent of rides generating an out-of-network charge. The average balance left to the patient tends to land somewhere around $450, and plenty of bills run well past that into four figures.
Why Congress Left It Out
The honest answer is that ground ambulances are a mess to regulate, and the mess is mostly about who runs them. Air ambulances are a smaller number of large operators, so pinning down a fair payment standard was tractable, and the law did it. Ground ambulances are thousands of separate operators, a lot of them municipal, each with its own rate set by a city or county, and setting a single federal payment rule across all of that was hard enough that Congress punted. It created an advisory committee to make recommendations instead of writing the protection into the law.
A committee is not a law. Until Congress acts on what that committee recommends, the ambulance remains the open door in an otherwise closed house. You are protected from the surprise anesthesiologist. You are not protected from the ride that got you to the anesthesiologist.
What Actually Protects You Depends on Your Zip Code
Because the federal law left the gap, a number of states stepped in and closed it themselves. More than a dozen have passed their own laws limiting what a ground ambulance can balance-bill an insured patient, and if you live in one of them, you have real protection that a neighbor two states over does not. This is one of those cases where the answer to "am I covered" is genuinely "it depends where you live," which is maddening but true.
There is also a catch inside the catch. State ambulance-billing laws generally cannot reach the kind of employer health plan known as self-funded, which is how a large share of people at bigger companies get their coverage, because those plans are governed by federal law and sit outside state insurance rules. So even in a state that banned the practice, someone on a self-funded plan may still be exposed. It is worth knowing which kind of plan you have, and human resources can tell you if you ask whether the plan is self-funded or fully insured.
What to Do With the Bill When It Comes
Say it happens anyway. A ride, and a few weeks later a bill for $600 that your insurer only partly paid. Do not just pay it, and do not ignore it either.
First, call your insurer and ask them to reprocess it, because emergency ambulance transport is often supposed to be paid at the in-network rate under your plan's own emergency-care terms even when the provider is out of network, and these get misprocessed all the time. Second, call the ambulance provider's billing office and ask two direct questions: whether they offer a financial hardship or need-based reduction, which many municipal services do and do not advertise, and whether they will accept the amount your insurer already paid as payment in full, which they sometimes will rather than chase you. And if you are in a state with an ambulance balance-billing law, say so, by name, because the person on the phone may be quietly counting on you not knowing. This is the same posture that works on the medical debt I wrote about with the premium increases hitting marketplace plans: the first number is rarely the final number, and the people who ask get a different bill than the people who pay on sight.
Know Where the Door Is Before You Need It
You cannot shop for an ambulance in the moment. Nobody expects you to. But you can find out today, while nothing is wrong, whether your state has closed this gap and whether your health plan is the kind those state laws can reach. Fifteen minutes now, a search for your state plus ambulance balance billing, and one question to human resources about your plan type.
It is a strange thing to have to research the price of an emergency. But the law drew a line and left the ambulance on the wrong side of it, and until that changes, the only protection in the gap is knowing the gap is there.
Ready to dig into the numbers? We have side-by-side breakdowns for every product mentioned in this article.