The Contractor Test Changed, and the Penalty Didn't Get Smaller
The federal rule for who counts as a contractor versus an employee flipped again in 2024, back to a broader test that pulls more workers onto the employee side. Guess wrong and the bill is back wages, doubled damages, and both halves of the payroll tax you never withheld.
The 1099 That Looks Like a Deal Until It Isn't
Paying someone as a 1099 contractor instead of a W-2 employee looks like a clean win for a small business. No payroll taxes to match, no benefits, no unemployment insurance, no overtime, less paperwork. For a shop watching every dollar, the temptation to call a worker a contractor is enormous, and a lot of businesses give in to it without thinking of it as a legal decision at all.
It is a legal decision, and the rules underneath it just moved. In 2024 the federal Department of Labor put a new classification test into effect, replacing the more business-friendly one that came before it, and the new test pulls more workers onto the employee side of the line. The penalty for getting it wrong did not move to match. It is still severe, still retroactive, and still capable of turning a few years of misclassification into a bill that dwarfs whatever you thought you were saving.
Here's What Actually Changed
The label on the worker was never what mattered. This is the thing most owners get backwards. It has never been up to you and the worker to simply agree that they are a contractor, sign something that says so, and have that be the end of it. The government applies its own test to the actual working relationship, and if the reality looks like employment, the paperwork calling it something else does not save you.
The 2024 rule went back to what is called a totality-of-the-circumstances economic reality test, which is a mouthful that means this: no single factor decides it, and an examiner weighs the whole relationship. How much control you exercise over how the work gets done. Whether the worker has a real opportunity for profit or loss based on their own judgment. How permanent the relationship is. Whether the work is central to your business or peripheral to it. Whether the worker is genuinely running their own independent operation with their own investment. The previous rule had leaned heavily on just two factors in a way that made it easier to classify someone as a contractor. The new one spreads the weight back across all of them, and the practical effect is that borderline cases now tip toward employee.
The Worker Who Is Almost Certainly an Employee
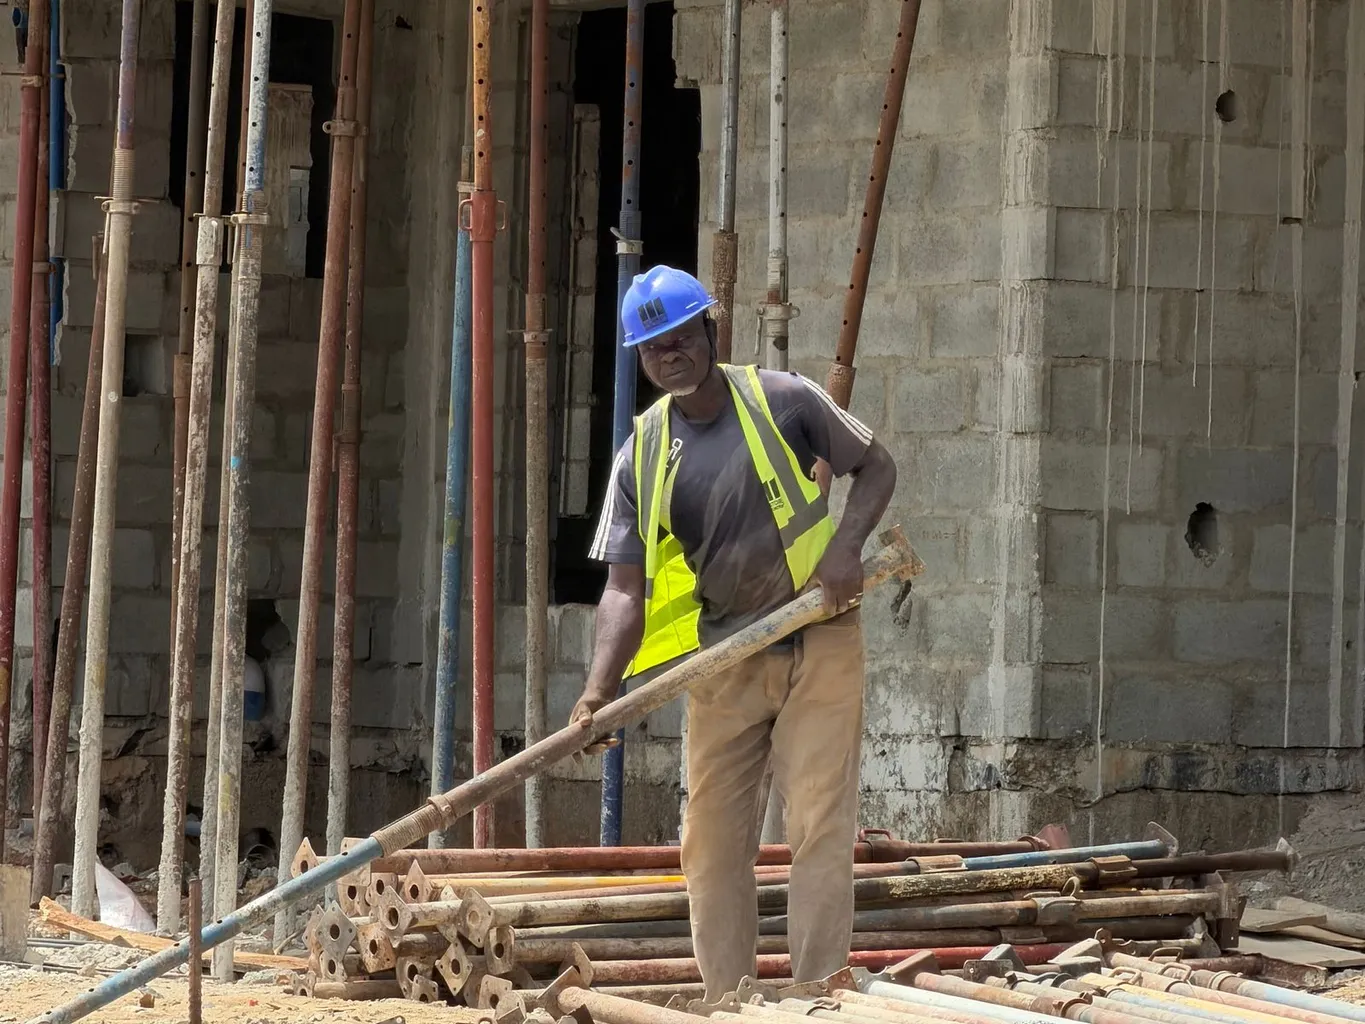
Abstractions do not help here, so picture the person who gets businesses in trouble. Someone who works only for you, or nearly so. Who shows up on a schedule you set. Who uses your tools, your systems, your account logins. Who does work that is the core of what your business sells, not a specialized outside project. Who has been with you for two years. Who has no other real clients and no separate business of their own.
You can pay that person on a 1099. Plenty of businesses do. But under the economic reality test, that person is an employee in all but name, because economically they depend on you the way an employee does, and calling them a contractor is exactly the arrangement the rule is built to catch. The tell is dependence. A real contractor runs a business that survives losing you as a client. Your longtime, full-time, works-only-here "contractor" does not, and that is the whole ballgame.
What the Mistake Actually Costs
Now the part that should focus the mind, because the downside here is not a slap. It compounds across every category of law the misclassification touched.
Start with wages. If that worker should have been an employee, they were owed overtime for years, time and a half on everything past forty hours a week, and under federal wage law a misclassification finding can carry liquidated damages, which is a polite term for doubling the back pay owed. Then the taxes. You did not withhold income tax, you did not pay the employer half of Social Security and Medicare, and you did not remit the employee half either, so the government can come after payroll taxes you never collected, and if it decides the misclassification was not a good-faith mistake, the exposure gets worse fast. Stack on state unemployment insurance you never paid into, workers' compensation you never carried, and, in some cases, retroactive benefits eligibility. One misclassified worker over three years can generate a five-figure liability without much effort. A handful of them can generate a number that ends a small business.
And it does not have to be an auditor who finds it. A single worker filing for unemployment after you let them go, or getting hurt with no workers' comp to cover them, can trigger the state to look at the relationship, and once one thread gets pulled the rest of your contractor roster tends to come with it. This is the same category of quiet, contract-level exposure I wrote about with the shake-up in non-compete enforcement: the terms you set on paper mean nothing the moment someone with authority decides the substance says otherwise.
The Test Is Federal, but It Isn't the Only Test
Here is a complication worth naming so you do not walk away thinking one rule governs everything. The Labor Department's economic reality test is the federal wage-law standard, but it is not the only classification test you answer to. The IRS runs its own analysis for tax purposes. And a number of states, California being the loudest, use a much stricter standard often called the ABC test, under which a worker is presumed to be an employee unless the business can prove all three of a short list of conditions, one of which is that the worker does something outside the company's usual course of business.
What that means in practice is that you can theoretically satisfy the federal test and still be offside under your state's, and the safe posture is to plan around the strictest test that applies to you, not the friendliest. If you operate in an ABC-test state, that is the bar to clear.
Classify for the Audit, Not for the Invoice
The move that gets businesses in trouble is classifying a worker for how it looks on this month's cash flow instead of how it will hold up when someone with authority examines it later. A contractor is cheaper this month. An audit finding is not, and the audit does not care what was convenient at the time.
Go look at anyone you pay on a 1099 and ask the honest version of the question, not the hopeful one. Do they work only for you, on your schedule, with your equipment, on the core of what you sell, with no real business of their own. If the answer to most of that is yes, you very likely have an employee wearing a contractor label, and the gap between those two things is a liability that grows every pay period you leave it in place. Fixing it forward is uncomfortable and it costs more per hour. It costs a great deal less than the version where a state examiner fixes it backward for you, with the doubling and the back taxes attached.
Ready to dig into the numbers? We have side-by-side breakdowns for every product mentioned in this article.